How a Credit Spread Option Works: Defined-Risk Strategies
Learn how a credit spread option caps downside risk while capturing net credit upfront. Read the full guide.
By Trader Faculty Team
Direct Answer
A credit spread option is a multi-leg vertical strategy where a trader simultaneously sells one option contract and buys another of the same underlying asset and expiration date at a different strike price. This position generates an immediate net cash credit in the trader's account while establishing a strictly defined maximum downside loss.
A credit spread option is an options trading strategy where you simultaneously buy and sell option contracts of the same class and expiration date, but at different strike prices, resulting in a net credit to your account upfront.
Many retail traders struggle to earn consistent returns because buying single options leaves them exposed to rapid time decay, while selling unhedged options carries catastrophic downside risk. Credit spreads solve both problems by capturing daily time decay while strictly bounding your maximum dollar risk.
This guide explains how credit spread options work, how to calculate your net credit and maximum risk, and how to execute Bull Put and Bear Call setups with clear risk rules.
Quick Takeaways
- A credit spread option involves selling one option contract while buying another of the same class with a different strike to capture a net credit upfront.
- Your theoretical maximum profit is capped at the initial credit received, while maximum risk is strictly defined by the width of the strike prices minus the credit.
- The strategy benefits directly from time decay and declining implied volatility as long as the underlying asset price stays beyond the short strike price.
What Is a Credit Spread Option?
Understanding the credit spread option meaning starts with recognizing it as a multi-leg vertical strategy that pairs a short and long option.
A credit spread option is a multi-leg vertical strategy that involves selling one option contract with a higher premium and simultaneously buying another option contract of the same underlying security and expiration date with a lower premium. Because the option you sell is worth more than the option you buy, your brokerage account receives a net cash credit upon opening the position.
Vertical spreads are defined-risk transactions. Unlike selling naked options, where market crashes or short squeezes can trigger uncapped losses, a credit spread pairs your short option with a protective long option. The long option acts as financial insurance, capping your maximum loss upfront.
Credit spreads differ fundamentally from debit spreads. In a debit spread, you pay cash upfront to enter the trade, needing the market to move significantly in your direction to profit. In a credit spread, you receive cash upfront, allowing you to profit if the market moves in your favor, stays flat, or even moves slightly against your position.
How Credit Spreads Work: Payoffs and Formulas
Credit spreads come in two primary configurations depending on your market outlook: a Bull Put Spread (used when you are bullish or neutral) and a Bear Call Spread (used when you are bearish or neutral).
Both configurations use vertical strike prices to lock in a net cash inflow while establishing a hard boundary on potential losses.
Net Credit = Short Option Premium - Long Option Premium
Maximum Profit = Net Credit Received
Maximum Loss = Width of Strike Prices - Net Credit Received
Breakeven (Bull Put) = Short Put Strike - Net Credit
Breakeven (Bear Call) = Short Call Strike + Net Credit
| Spread Type | Market Outlook | Leg 1 (Short Leg) | Leg 2 (Long Protective Leg) | Max Profit Condition |
|---|---|---|---|---|
| Bull Put Spread | Bullish / Neutral | Sell higher strike Put | Buy lower strike Put | Price stays above short Put |
| Bear Call Spread | Bearish / Neutral | Sell lower strike Call | Buy higher strike Call | Price stays below short Call |

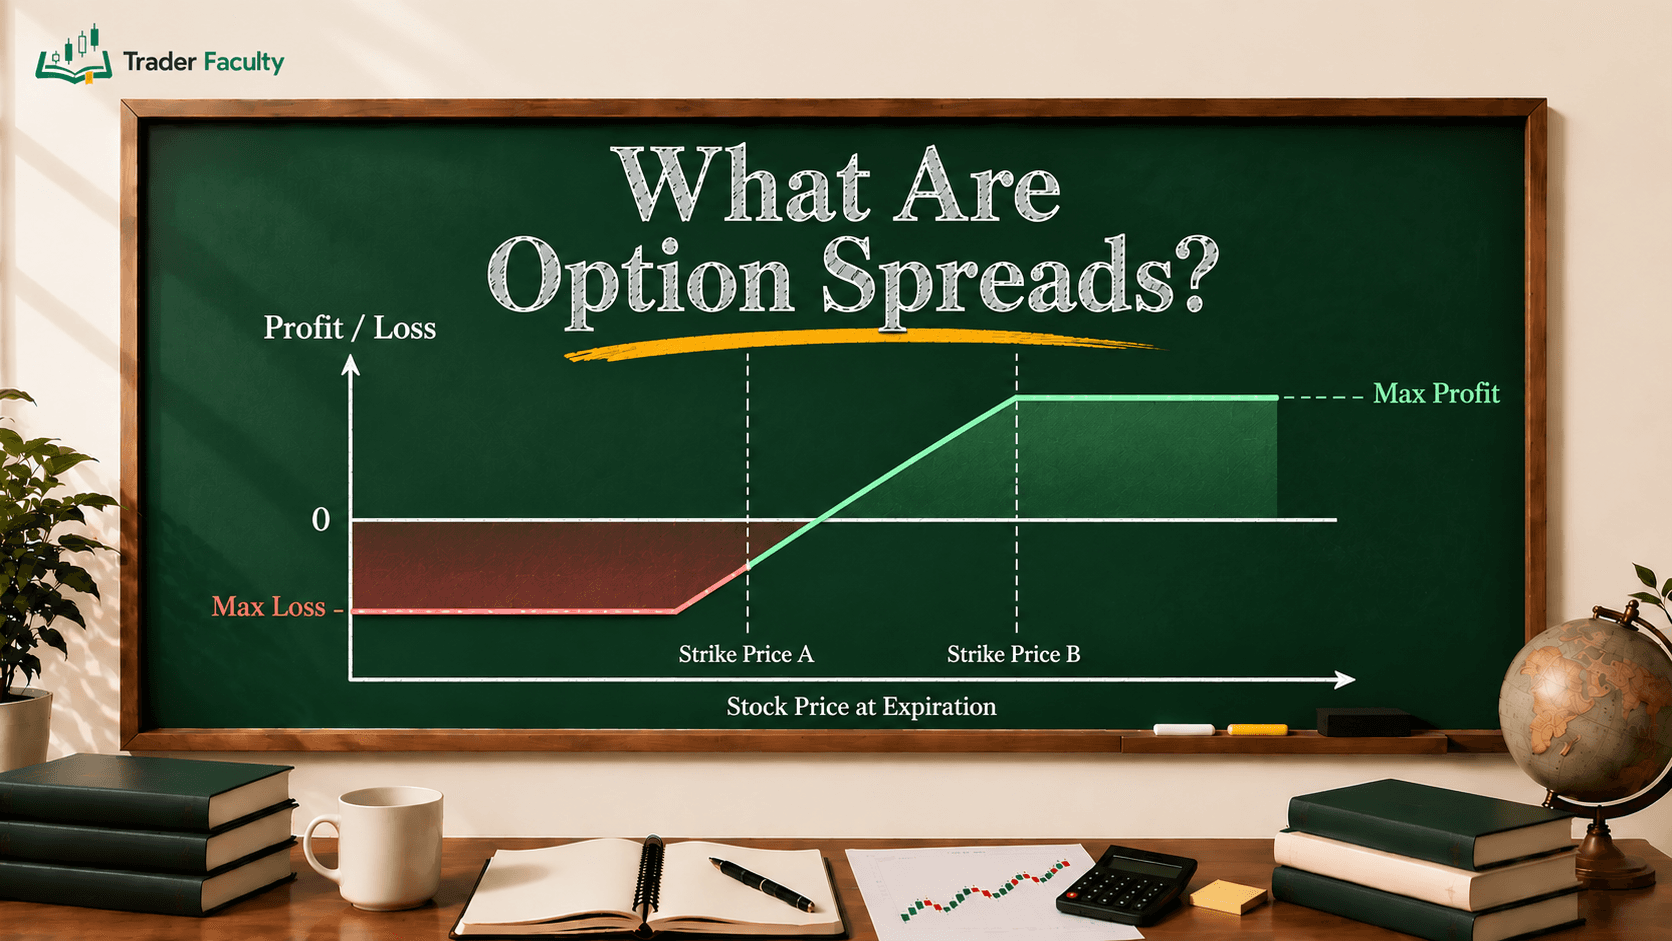
Figure: Bull Put Credit Spread Payoff Diagram
Worked Example: Entering a Bull Put Spread
To see how the payoff math works in practice, consider an underlying stock trading at $100 per share. You believe the stock will stay above $95 over the next 30 days.
To structure a Bull Put Spread, you execute two trades simultaneously as a single order:
- Sell 1 Put contract at the $95 strike for a $2.50 premium credit.
- Buy 1 Put contract at the $90 strike for a $0.80 premium debit.
Your initial cash flow is a net credit of $1.70 per share ($2.50 credit minus $0.80 debit). Because standard equity option contracts cover 100 shares, you collect $170 in net cash upfront.
Your maximum downside exposure is defined by the distance between the two strike prices ($95 minus $90 = $5.00 width), minus the credit received ($1.70). This leaves a maximum loss of $3.30 per share, or $330 per contract.
Your broker will hold $330 per contract as required margin collateral to secure the position. If the stock expires above $95, both puts expire worthless and you retain the full $170 profit. If the stock crashes to $80, your maximum loss remains strictly capped at $330 because your long $90 Put protects you from further downside.
Key Advantages and Structural Trade-Offs
The main structural advantage of a credit spread is time decay. Options lose extrinsic value every day as they approach expiration. As an option seller, time decay works in your favor, reducing the cost to buy back the spread for a profit as expiration approaches.
Additionally, credit spreads benefit from decreases in implied volatility (a market measure of expected future price swings). When implied volatility falls, option premiums contract across the board. This allows credit spread traders to close positions early at a lower repurchase price even if the underlying asset price remains unchanged.
The primary trade-off is capped upside potential. No matter how far the underlying stock rallies, your maximum profit cannot exceed the net credit collected at trade entry. Furthermore, brokers require you to lock up margin capital equal to the full strike width, which reduces your available cash for other trades while the spread remains open.
Managing Risk: Early Assignment and Exit Rules
While vertical credit spreads cap your maximum potential loss, active position management is critical to protecting your trading balance.
If the underlying asset price breaches your short strike price, the position moves In-The-Money (ITM). This creates the risk of early assignment — where the option buyer exercises their right, forcing you to take a long or short stock position unexpectedly. The risk of early assignment is lower when option contracts retain extrinsic value, but rises sharply during expiration week or right before dividend dates.
Execution friction also affects real-world performance. Multi-leg option orders pass through wider bid-ask spreads (the difference between the highest price a buyer pays and the lowest price a seller accepts) than single-leg trades. Entering or exiting illiquid option contracts can result in slippage that erodes net income.
To protect capital, disciplined options traders commonly follow structured exit rules rather than holding positions blindly to expiration.
Common risk protocols include:
- Closing positions early when reaching 50% of maximum potential profit
- Rolling to a later expiration around 21 days to expiration to reduce gamma risk
- Setting a hard stop-loss at 100% to 200% of the initial credit collected.
Common Mistakes Beginners Make with Credit Spreads
New options traders often misjudge entry dynamics, leading to avoidable losses:
- Selling Spreads Before Earnings: Entering credit spreads right before major corporate announcements subjects you to extreme volatility expansions that can quickly blow through both strike prices.
- Ignoring Bid-Ask Liquidity: Trading option chains with low daily volume leads to heavy slippage when trying to lock in profits or close losing positions.
- Holding Contracts Into Expiration Week: Remaining in short options during the final days before expiration exposes your account to sudden pin risk and early assignment friction.
Executing credit spreads cleanly is an essential building block when learning day trading for beginners.
Credit Spread Option vs. Debit Spread Option
Understanding whether to enter a credit spread or a debit spread depends on your volatility expectations and directional stance.
| Feature | Credit Spread Option | Debit Spread Option |
|---|---|---|
| Initial Cash Flow | Net Credit (Cash Inflow) | Net Debit (Cash Outflow) |
| Primary Directional Bias | Neutral to Slightly Directional | Moderately to Strongly Directional |
| Impact of Time Decay | Positive (Time helps position) | Negative (Time hurts position) |
| Ideal Volatility Environment | High Implied Volatility (Sell high IV) | Low Implied Volatility (Buy low IV) |
| Maximum Profit | Capped at Initial Net Credit | Capped at (Width of Strikes - Net Debit) |
| Maximum Loss | Capped at (Width of Strikes - Credit) | Capped at Initial Net Debit Paid |
Conclusion
Credit spread options provide systematic traders with a defined-risk framework to capture option premium while maintaining absolute control over potential downside losses. By selecting liquid strike prices, managing time decay, and adhering to strict exit rules, you can maintain consistent portfolio risk control across volatile market cycles.
With the mechanics of a credit spread option explained above, you can now apply the Bull Put and Bear Call frameworks with confidence.
Trading always carries the risk of losing capital, so treat every setup as a probabilistic risk model rather than a source of guaranteed income.
Want to master structured multi-leg execution and portfolio risk management? Learn how to integrate credit spreads into a complete risk-defined framework inside our Build Your Trading System guide.
Frequently Asked Questions
What is a credit spread option example?
A credit spread option example is a Bull Put Spread where a trader sells a $95 Put for a $2.50 credit and buys a $90 Put for a $0.80 debit on a $100 stock. The trader receives a net credit of $1.70 ($170 per contract) upfront. The maximum loss is capped at $3.30 ($330 per contract), which occurs if the stock drops below the $90 long strike at expiration.
Is a credit spread option risk-free?
No options strategy is risk-free. While a vertical credit spread caps your maximum dollar exposure using a protective long leg, you can still lose your collateral up to the maximum loss limit if the underlying asset price moves against your short strike price before expiration.
What is the difference between a credit spread and a debit spread?
A credit spread generates a net cash inflow upfront when you enter the position by selling a higher-priced option and buying a lower-priced one. A debit spread results in a net cash outflow at entry because you buy a higher-priced option and sell a lower-priced one to offset costs.
How much capital do you need to trade a credit spread?
The capital required to open a credit spread equals the margin collateral held by your broker. This collateral is calculated as the width of the strike prices minus the net credit received, multiplied by 100 shares per contract. For a $5 wide spread receiving $1.70 in credit, the required margin collateral is $330 per contract.
What happens if a credit spread option goes in the money?
If the underlying stock price moves past your short strike price, the short option contract becomes In-The-Money (ITM). This increases the risk of early assignment, where the contract buyer exercises their option and forces you to buy or sell the underlying shares. Traders usually close or roll losing spreads before expiration to manage this risk.
The Trader Faculty Team writes and reviews every guide together — pairing hands-on market experience with a curriculum-first approach to trading education. One good syllabus, taught in the order that makes you better.